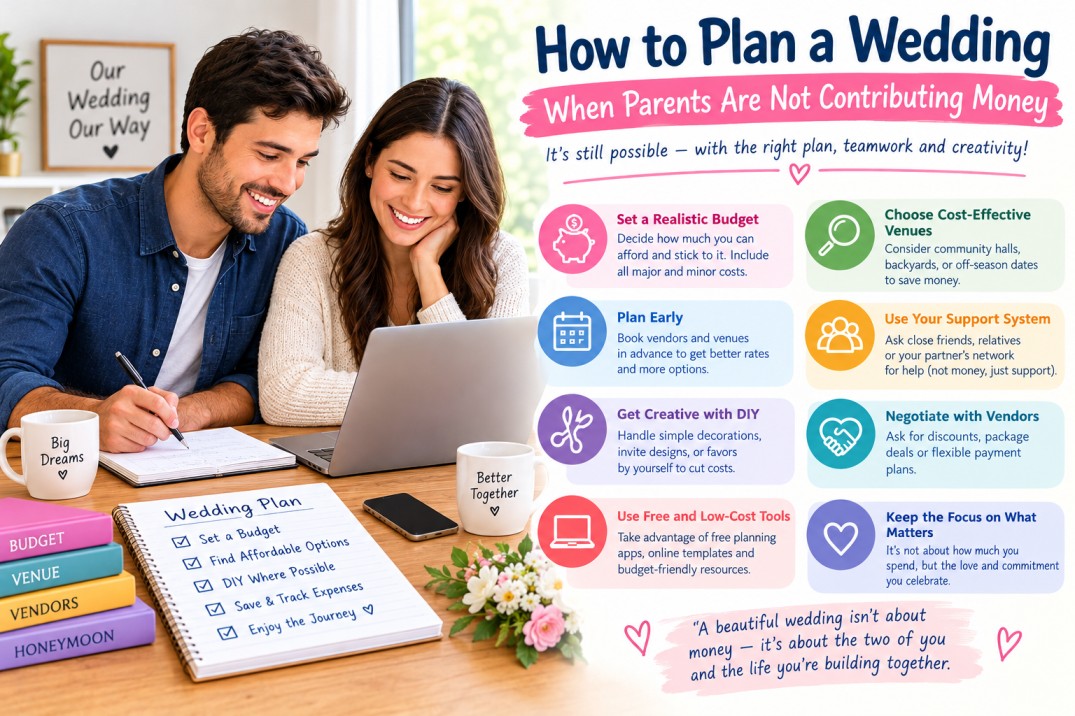
Most wedding advice quietly assumes that someone else is helping to pay. Budget templates list “contributions from family” as a line item. Planning timelines assume a cushion of money that appears when needed. If your parents aren’t contributing, whether they can’t, won’t, or were never part of the picture, much of that advice doesn’t fit your situation.
The good news is that a wedding funded entirely by the two of you can be just as beautiful, meaningful, and well organized as any other. It simply requires a different starting point. Instead of asking “what do we want, and how do we pay for it?”, you ask “what can we afford, and how do we make that feel like exactly what we wanted?”
This guide walks through the whole process: the emotional side, the money conversation, building a budget from nothing, choosing where to spend and where to save, managing family expectations, and sticking to a plan that keeps you out of debt. Examples use round numbers in dollars, but the formulas and strategies work in any currency.
Why Parents Don’t Contribute (and Why Their Reason Changes Your Plan)
Before you plan anything, it helps to understand why the money isn’t coming. The reason shapes how you talk to them, how you feel about it, and what other kinds of help might be possible.
They Genuinely Cannot Afford It
Many parents are on fixed incomes, paying off debt, supporting other relatives, or recovering from financial setbacks. Some are quietly embarrassed that they can’t help, which can make them withdraw from the planning entirely. If this is your situation, the most useful thing you can do is remove the pressure. Tell them early that you’re planning around your own funds, so they never have to confess what they can’t give.
They Believe the Couple Should Pay
In some families, paying for your own wedding is simply the norm, especially for couples who are older, financially independent, or living together already. These parents aren’t being cold. They may have paid for their own weddings, or they may see their role as emotional rather than financial. A friendly conversation usually shows that they plan to help in other ways.
They Are Willing but Conditional
Sometimes parents offer money, but the offer comes with strings: a bigger guest list, a specific venue, a religious ceremony, or approval over vendors. If the conditions don’t match what you want, turning the money down is a valid choice. Funding your own wedding is also buying the freedom to make your own decisions.
Money Is Tied Up in Conflict
When there’s estrangement, a divorce, or a long-running disagreement, money can become a pressure point, and a withheld contribution may be about something else entirely. In that case, the practical plan is to build a wedding that doesn’t depend on anyone’s change of heart.
Your Partner’s Parents Are Contributing but Yours Aren’t
This situation creates its own tension, which we’ll address in detail later. For now, note that it’s common, and it doesn’t have to create inequality between you and your partner.
Start With the Emotional Side, Because It Affects Every Decision
Wedding planning without parental support can bring up feelings that surprise people. Dealing with them early prevents them from leaking into budget decisions.
It’s Normal to Feel Disappointed
You may have imagined a certain kind of wedding, or you may be comparing yourself to friends whose parents paid for everything. Disappointment doesn’t mean you’re ungrateful or materialistic. It usually reflects a wish to feel supported. Acknowledge that feeling and share it with your partner or someone you trust, rather than carrying it silently.
Separate Money From Love
Many people interpret a parent’s financial contribution as a measure of love or approval. In reality, money tends to reflect ability, culture, and priorities, not affection. A parent who gives you no money but shows up, listens, and celebrates with you may be giving you more than one who writes a check and criticizes every detail.
Watch for Resentment Building Up
Resentment is the real risk. If you quietly resent your parents throughout the planning process, it can damage the relationship long after the wedding is over. If you notice it growing, say it out loud to your partner, and consider whether a direct, calm conversation with your parents might clear the air.
Reframe the Situation as Ownership
Paying for your own wedding means no one else has a claim on it. You choose the guest list, the venue, the menu, and the traditions. Many couples who fund their own weddings later say that the day felt more authentically theirs.
How to Talk to Your Parents About Money
The biggest planning mistake in this situation is assumption. Some couples assume parents will help, and some assume they won’t, and both can lead to hurt feelings. A single clear conversation avoids this.
Have the Conversation Early
Talk before you book anything or set a budget. If you wait until after you’ve fallen in love with a venue, any hint of contribution or refusal will feel loaded.
Use a Script That Makes It Easy to Say No
Directness works better than hinting. Here is a version you can adapt:
“We’ve started planning the wedding, and we want to build the budget around what we can fund ourselves. We wanted to ask whether you were planning to contribute anything, even something small. Either answer is completely fine, and we’ll plan around it. We just want to be clear so no one is surprised.”
This wording works because it gives them an exit, sets the expectation that you’re self-funding, and removes any sense that you’re pressuring them.
Ask About Non-Financial Help
If the answer is no money, follow with: “Is there anything else you’d enjoy helping with?” Parents often feel better when they can contribute something, and many are happy to offer help they can afford: hosting a rehearsal dinner, cooking, lending a car, giving up a garden or home for photos, helping with setup, or tapping relatives who have useful skills.
Choose the Right Setting
Avoid bringing it up in the middle of a family gathering, a holiday, or an argument. A quiet phone call or a private conversation at home gives everyone room to respond honestly.
Decide Your Response Beforehand
Think through how you’ll react to each possible answer. If they say no, you can reply, “Thank you for being honest, that’s totally fine.” If they say yes but with conditions, you can say, “Thank you, we’d love to think about it and get back to you.” Having words prepared prevents you from saying something you regret.
What to Do If Parents Offer Money Later, or Withdraw an Offer
Money situations change. Both directions require a plan.
If They Offer Money After You’ve Budgeted
Welcome it, but don’t let it change your core plan right away. Ask what the offer is, whether it’s a gift or a loan, and whether any conditions are attached. Then decide whether to use it to reduce your savings burden, upgrade a priority item, or add to your contingency fund.
Get Clarity on Gift Versus Loan
A vague “we’ll help” can later become “you owe us.” If money is offered, ask gently: “Is this a gift, or would you like us to repay it?” Whatever the answer, agree on it clearly, and consider writing it down for a loan. Families can be damaged by misunderstandings about money.
If a Parent Offers and Then Withdraws
This happens more than people admit. Job loss, illness, or changed circumstances can make a promised contribution disappear. This is why a conservative rule helps: never commit to deposits based on money that isn’t yet in your account. Treat promised money as a bonus, not as part of the budget, until it arrives.
If Money Comes With Strings
If the conditions conflict with your wishes, you have three options: accept the money and the conditions, negotiate the conditions, or decline politely. A good decline is simple: “Thank you so much for the offer. We’ve decided we want to make these decisions ourselves, so we’ll keep our wedding within what we can fund.” You can do this without drama and without criticizing them.
Build Your Budget From Zero
Without parental contributions, your budget isn’t a guess or a national average. It’s a number you can calculate.
Use the Wedding Fund Runway Formula
Add your current wedding savings to what you can realistically save each month until the wedding. Here’s an example:
- Current savings: $5,000
- Monthly savings: $800
- Months until wedding: 15
- Total: 5,000+(800 × 15) = $17,000
- Contingency (10 percent): $1,700
- Spendable budget: $15,300
That final number is your wedding budget. It isn’t what the internet says weddings cost; it’s what you can pay for without debt.
Be Honest About Your Monthly Savings Number
Many couples overestimate what they can save. Check your actual spending for the past three months, and choose a number you could keep up even in a tighter month. It’s better to underestimate and be pleasantly surprised than to promise yourself more and fall short.
Set Savings Checkpoints
Divide your timeline into checkpoints. For example, at month six you should have a specific amount saved. If you’re behind at a checkpoint, you have time to adjust before you’ve committed to major vendors. This is one of the simplest ways to prevent budget problems from growing unnoticed.
Keep the Wedding Fund Separate
Open a dedicated savings account and set up an automatic monthly transfer. Separating the money makes it harder to spend on other things and makes progress visible. If your account earns interest, even a small amount helps.
Don’t Budget on Gifts From Guests
Cash gifts from guests may be generous, but they arrive after the wedding, after the bills are due. Treat them as a bonus for your honeymoon, savings, or home. Counting on gift money to cover wedding costs is a common route to debt.
Include Costs That Are Easy to Forget
Add lines for tax and service charges, tips, marriage license and legal fees, alterations, postage, rentals, emergency supplies, and a small amount for last-minute needs. These can add up to a significant percentage of your total.
Divide the Budget by Percentage
Once you have a total, a percentage-based allocation gives you a starting structure. These are guidelines you can adapt:
- Venue, food, and drink: 45 to 50 percent
- Photography and video: 10 to 12 percent
- Attire, hair, and makeup: 7 to 10 percent
- Music and entertainment: 5 to 8 percent
- Flowers and décor: 5 to 8 percent
- Stationery and postage: 2 to 3 percent
- Officiant, legal, and miscellaneous: 3 to 5 percent
- Contingency: 10 percent
Adjust Based on Your Priorities
If photography matters most to you, increase that category and reduce decoration. If food is your focus, give catering a larger share. The percentages are a starting point, not rules.
Revisit the Allocation After Getting Quotes
Your first allocation will often change once real prices arrive. When one category goes over, take money from another before touching the contingency.
Decide Your Priorities Before You Price Anything
Couples overspend when everything feels equally important. Deciding priorities in advance protects you from impulse upgrades.
The Top-Three Method
Each of you privately writes the three elements you care about most. These might be the meal, the music, the photography, the venue’s atmosphere, or having a certain person present. Compare lists. Where your priorities overlap, invest the most. Where they don’t, discuss and compromise.
The “Would We Miss It?” Test
For every line item, ask: “If this weren’t there, would we notice or care?” Many popular items fail this test, including favors, elaborate welcome signs, extra décor, and custom stationery details. Items that pass tend to be the meal, the photos, the people, and the atmosphere.
Separate Needs, Wants, and Extras
Group every item into three categories. Needs are the legal and structural elements: the marriage license, an officiant, a venue, and food. Wants are things that make the day more personal. Extras are nice-to-haves. Fund needs first, then wants in order of importance, and treat extras as optional.
Let Go of “Shoulds”
Many people spend money on things because they feel they’re supposed to: a certain number of bridesmaids, a bouquet toss, a multi-tier cake. If an item has no meaning for you, skipping it isn’t a loss.
Start With the Guest List, Because It Controls Almost Everything
Few decisions affect your cost as much as headcount. Food, drink, tables, chairs, linens, invitations, favors, and venue size all scale with the number of guests.
Calculate Your Cost Per Guest
Add together everything that increases with headcount, such as catering, beverages, rentals, and service fees. Divide by the number of guests. If the result is $95, each additional guest adds about $95. Ten extra guests cost roughly $950. Seeing this number makes the guest list concrete.
Build a Three-Tier List
Tier A is people you can’t imagine the wedding without, usually immediate family and closest friends. Tier B is people you’d love to see but could live without. Tier C is people you’d invite mainly out of obligation. Fill Tier A first, add Tier B as the budget allows, and treat Tier C as optional.
Set a Hard Number Early
Decide on a maximum headcount before you look at venues. If you let the list grow organically, it will keep expanding. A hard number gives you a simple answer when someone asks, “Can we add a few more?”
Prepare for Pressure From Extended Family
Even parents who don’t contribute may still ask to invite relatives or family friends. You can respond: “We’re keeping the guest list small because we’re paying for the wedding ourselves. We aren’t able to add more people.” Because it’s about the budget, it’s easier to explain and harder to argue with.
Don’t Forget Plus-One Policies
Plus-ones can inflate your list quickly. Consider offering them only to guests in serious relationships, or only to wedding party members. Apply the rule consistently so no one feels singled out.
Avoid the Hidden “Invite Chain”
Inviting one coworker can lead to inviting a whole team. Decide in advance how you’ll handle groups, and keep the rule simple, such as “no work colleagues” or “only those we see outside of work.”
Choose a Date and Time That Save Money
You can reduce costs by thousands without changing the quality of your wedding, simply by choosing your date wisely.
Consider Off-Peak Days
Saturdays in peak season are the most expensive. Fridays, Sundays, and weekdays are often discounted, and many venues will quote lower prices when you ask. Discounts aren’t always advertised, so ask directly.
Consider Off-Peak Months
Slower seasons usually bring lower rates from venues, photographers, and florists. Choose a season that fits your region’s weather, and have a backup plan for outdoor events.
Choose a Different Time of Day
A morning or afternoon wedding with a brunch or lunch reception costs less per guest than an evening dinner. It generally uses less alcohol and ends earlier, which can reduce overtime charges.
Avoid Holiday Weekends and Major Local Events
Holiday weekends increase demand and prices, and your guests may face travel costs. Major events such as festivals or sports tournaments can raise hotel prices and make travel harder.
Stay Flexible, Then Book Quickly
If you’ve found a venue that fits your budget, ask for its available discounted dates and choose from those. Being flexible about the date gives you leverage. Once you decide, book promptly, since good dates disappear.
Choose a Venue That Reduces Other Costs
The venue is usually your largest expense, but the right choice can lower your costs elsewhere.
Understand What the Price Includes
Some venues include tables, chairs, linens, tableware, and basic lighting. Others are empty spaces, which means you’ll rent everything separately. A venue with a higher fee that includes rentals may cost less overall than a cheaper empty space.
Look Beyond Traditional Wedding Venues
Consider community halls, public parks and gardens, restaurants with private rooms, breweries, libraries, museums, university spaces, or a relative’s or friend’s property. Always confirm permits, insurance requirements, restroom access, power supply, parking, noise rules, and rain backups.
Use One Location for Everything
Holding the ceremony and reception in the same place removes the cost of a second venue and transportation. It also reduces the time guests spend between events, which can let you shorten your vendor hours.
Ask About Hidden Venue Fees
Ask for a complete written breakdown. Common extras include service charges, administrative fees, cleaning fees, security deposits, overtime rates, parking or valet charges, corkage fees, cake-cutting fees, and mandatory minimum spending.
Ask Whether Outside Vendors Are Allowed
Some venues require you to use their preferred caterer, bar, or décor providers. Others allow outside vendors, which gives you more flexibility to compare prices. This single question can change your whole budget.
Check Cancellation and Rescheduling Terms
Before paying a deposit, understand what happens if you need to change the date, reduce the guest count, or cancel. Flexible terms protect you if circumstances change.
Spend Wisely on Food and Drink
After the venue, food and drink is usually your largest category, and it’s one that guests notice immediately.
Compare Service Styles
Plated dinners typically require the most staff. Buffets can reduce staffing costs but need more space and time. Family-style service creates a warm atmosphere but may involve more food. Stations, tacos, barbecue, or appetizer-and-dessert receptions can be economical, depending on your region and caterer.
Match the Menu to the Time of Day
If your wedding falls between meal times, guests expect lighter food. An afternoon reception with appetizers and desserts can feel generous without requiring a full dinner.
Reduce Choices to Reduce Cost
Offering a choice of three entrées increases complexity and often cost. A single well-prepared menu, with vegetarian and dietary options available on request, can lower prices and reduce waste.
Be Strategic About Alcohol
Alcohol can become a hidden budget drain. Options include beer and wine only, a signature cocktail, a limited bar window, or serving alcohol only during dinner. Check venue policies and local laws before buying your own supply, since some venues require licensed bartenders. If your family or culture doesn’t center on alcohol, a well-planned drink menu with mocktails, specialty teas, or fresh juices can be both affordable and memorable.
Plan the Cake Differently
A small display cake for the cutting, supported by sheet cake or cupcakes from the kitchen, gives you the photo without paying for a large tiered cake. Pie, donuts, cultural sweets, or a family recipe are good alternatives.
Ask Caterers About Budget Packages
Tell the caterer your per-person budget and ask what they can design within it. Many are willing to adjust menus. Ask about service charges, staffing minimums, and whether rentals or cleanup are included.
Don’t Forget Late-Night Needs and Vendor Meals
Vendors such as photographers and DJs often need meals, and guests may want food later in the evening. Ask your caterer how they handle these, and include them in your count.
Photography and Video: Where to Invest and Where to Trim
Photos are what you keep, so many self-funded couples decide to protect this budget line.
Pay for Quality Over Hours
If you can’t afford full-day coverage, choose a skilled photographer for fewer hours. Focus on the ceremony, couple portraits, key family moments, and the first part of the reception.
Review Complete Galleries
Highlight reels show only the best moments. Ask to see a full wedding gallery from a single event, which shows consistency and how the photographer handles different lighting and situations.
Clarify Usage and Delivery
Get in writing how many edited images you’ll receive, when you’ll get them, whether you can print them, and how long the gallery will be stored. Avoid vague promises.
Consider Emerging Photographers
A newer photographer with a strong portfolio may charge less than an established one. Check reviews, ask for references, and make sure they have backup equipment and a plan in case of illness.
Be Careful With Friends and Guests as Photographers
A talented friend can be a wonderful option, but they’ll be working instead of celebrating, and an inexperienced one may struggle with low-light or fast-moving moments. If you go this route, give them a shot list and agree on expectations in advance.
Think Hard About Video
Video can be valuable, but it’s often an optional add-on. If you can’t afford both, many couples prefer to prioritize photographs and arrange a few guest-recorded clips.
Attire, Hair, and Makeup Without the Wedding Markup
Items labeled “wedding” often cost more than similar items that aren’t.
Explore Alternatives to a New Gown or Suit
Options include sample sales, pre-owned dresses, rentals, bridesmaid or formal dresses in white or ivory, and non-bridal retailers. For suits, consider a well-tailored suit you can wear again, or renting for the day.
Budget for Alterations
Alterations can be a significant and sometimes surprising cost. Include them in your plan, and schedule fittings well before the wedding.
Choose Partner Attire That Coordinates, Not Matches
Coordinating outfits can reduce stress and cost. You don’t need an identical color scheme everywhere if it adds to your expenses.
Simplify Beauty Services
Book only essential services, or ask a skilled friend to help. Do a trial run beforehand to avoid surprises. If you hire a professional, ask for a package that covers only the people who need it most.
Limit Wedding Party Costs
If you have attendants, avoid requiring expensive outfits. Consider letting them choose their own clothes within a color range. Asking friends to spend heavily when you’re budgeting carefully can create tension.
Décor, Flowers, and Stationery: Make Less Look Intentional
This is a category where small choices can save a lot, because much of what couples buy is rarely noticed.
Spend on One Focal Point
Choose one area where décor really matters, such as the ceremony backdrop or the head table, and keep everything else simple. One strong visual feels more purposeful than scattered decorations.
Choose Seasonal and Local Flowers
Flowers in season are generally cheaper and fresher. Consider greenery, potted plants, dried arrangements, or a single type of flower in multiple vases. Reusing ceremony flowers at the reception can also reduce costs.
Choose Candles, Greenery, and Lighting Over Props
Lighting is often a better investment than props. Candles, string lights, and warm bulbs can change the mood of a room at a modest cost, but check venue fire and safety rules.
Keep Stationery Simple
Digital invitations and a wedding website can cover most communication, and printed items can be limited to what you need. If some guests, such as older relatives, prefer paper, print only those. Remember to include postage, envelopes, and extra copies for mistakes.
Reuse, Rent, and Resell
Consider renting décor, borrowing from friends, or buying items you can resell afterward. Some couples arrange to sell or donate décor items after the wedding.
Music and Entertainment on a Smaller Budget
Music shapes the energy of the day, but it doesn’t need to be expensive.
Match the Music to the Moment
Live music is most valuable during the ceremony, and a playlist can handle the rest. You can invest in a musician for the ceremony and use a curated playlist for the reception.
Use a Sound System and a Trusted Person
At small weddings, a rented speaker system and a reliable friend or venue staff member can replace a DJ. Create a playlist with a clear timeline and a “do not play” list.
Ask DJs About Shorter Packages
If you do hire a DJ, ask about shorter packages or off-peak discounts. Compare what’s included, such as microphones, lighting, and announcements.
Plan Meaningful Moments
Your first dance, a parent dance, or a song with personal meaning matters more than a long dance floor playlist. Plan those and keep the rest flexible.
The Hidden Costs Most Couples Forget
Budgets often fail not because of big items but because of small ones that were never included.
Taxes, Service Charges, and Tips
Many quotes don’t include tax or service charges, and gratuity may be expected. Ask whether each quote is “all-in” and what the final total would be.
Overtime and Timeline Changes
If your ceremony starts late or your reception runs over, vendors may charge extra. Build a realistic timeline with buffers.
Rentals and Delivery
Chairs, tables, linens, heaters, tents, and lighting may involve delivery, setup, and pickup fees. Ask whether rental prices include these.
Transportation and Accommodation
Consider parking, shuttles, and lodging for you, your family, and vendors who travel. A hotel block may reduce costs but check minimum commitments.
Permits, Licenses, and Legal Fees
Marriage licenses, venue permits, and any special event permissions may be required. Check requirements and deadlines for your location.
Emergency and Day-of Supplies
Prepare an emergency kit with sewing supplies, pain relievers, stain remover, snacks, and phone chargers. These small items can prevent bigger problems.
Thank-You Gifts and Notes
Gifts for helpers, tips for vendors, and thank-you cards add up. Budget a small amount for them.
DIY and Borrowed Help: Use Them Carefully
DIY and help from loved ones can save money, but only when used wisely.
Choose Low-Risk Projects
Good DIY items include simple signage, playlists, small greenery arrangements, printed programs, and desserts for a small group. These projects are manageable and don’t ruin the day if they go wrong.
Avoid High-Stakes DIY
Don’t take on anything that has to be perfect at a precise moment, such as catering for a large crowd, photography, or complex floral installations. Mistakes in these areas are hard to fix.
Calculate the True Cost
Include materials, tools, mistakes, shipping, and the value of your time. If a project requires 15 hours and saves $40, it may not be worth it.
Delegate Clearly
If friends or relatives help, assign specific tasks and tell them what is expected, when, and where. Avoid giving someone a vague role on the day itself.
Thank Helpers Properly
Unpaid help still has a cost in time and effort. A thank-you gift, a meal, or a public acknowledgment shows appreciation.
Negotiate With Vendors (and Know What to Say)
When you pay for your own wedding, you can often improve your price by asking thoughtful questions.
Share Your Budget Range Honestly
You might say: “We’re working with a budget of around X for this service. What could you offer within that?” Many vendors will suggest packages or adjust services. If a vendor refuses to work within any budget, you’ve learned something valuable.
Request Multiple Quotes
Get at least three quotes for major categories, using the same details so you can compare. Look at what’s included, not just the total.
Ask About Off-Peak and Weekday Discounts
Vendors often have flexibility on less popular dates or times. Asking directly is the best way to find out.
Ask About Bundles
Photographers may bundle photo and video, caterers may include rentals, and venues may include coordination. Ask whether bundling lowers the price, then check that you actually need everything included.
Read Every Contract
Contracts should list services, dates, times, payment schedule, cancellation and refund terms, backup plans, and what happens if the vendor cannot attend. Ask questions before signing, not after.
Keep Communication in Writing
Confirm key decisions by email, so you have a record. This protects both sides if details are misremembered.
Plan Your Payments and Protect Your Cash Flow
Even a well-planned budget can cause stress if payments arrive at the wrong time.
Build a Payment Calendar
List every deposit and final balance with its due date. This shows months when large payments overlap, so you can negotiate different schedules or adjust savings.
Keep Your Contingency Untouched
Your 10 percent contingency isn’t extra spending money. It’s for unexpected costs, such as price changes, weather backups, or extra guests. If you don’t use it, you keep it.
Track Spending in Real Time
Use a spreadsheet or app with columns for estimated cost, actual cost, amount paid, and amount remaining. Update it whenever you pay or receive a quote.
Think Carefully About Credit Cards
Paying vendors by credit card can provide some purchase protection, and rewards can add value, but only if you pay the balance in full. Carrying a balance at high interest can cancel any benefit.
Treat Loans as a Last Resort
If you consider financing, calculate the total repayment, not just the monthly payment. Ask whether a smaller wedding would feel just as meaningful. A helpful rule is to avoid borrowing for anything you couldn’t comfortably repay within a few months after the wedding.
Consider Wedding Insurance Only if It Fits
If you’ve made large non-refundable deposits, insurance may be worth considering. Read what’s covered, what’s excluded, and whether the cost makes sense compared with the amount at risk.
Money From Other Sources: Gifts, Registries, and Contributions
Even if your parents aren’t contributing, other sources of support may exist. Handle them carefully.
Accepting Help From Other Relatives
Grandparents, aunts, uncles, or siblings may offer to help. Ask whether the offer is a gift or loan, and whether there are expectations. Be gracious and clear.
Setting Up a Registry
If you already own household items, consider a cash or experience registry, or a donation to a cause you care about. Phrase it simply on your website, and avoid requesting specific amounts.
Think Before Crowdfunding
Asking guests to fund the wedding itself can offend some people. Funds for a honeymoon, home, or future goals are generally received more warmly than funds for the reception.
Accept Practical Help
If a friend offers to bake, drive, set up, or officiate, accept the help that fits your plan and define the role. Specific help is more useful than a vague “let me know.”
Understand Gift Rules Where You Live
In some countries, large monetary gifts may be reportable or taxable. If someone gives you a substantial amount, check local rules or ask a qualified professional.
Manage Family Politics Without Losing Your Peace
Without parental contributions, you may still face family opinions. Handling them early protects your relationships and your sanity.
When Parents Aren’t Paying but Still Have Opinions
You can say: “Thank you for your ideas. Because we’re paying for the wedding ourselves, we’re making the final decisions together.” Said kindly and calmly, this respects them while keeping your boundaries.
Give Parents Roles That Don’t Depend on Money
Offer a meaningful role: a toast, a reading, a blessing, a special dance, or time with you on the morning of the wedding. Being included often lowers the desire to control details.
When Your Partner’s Parents Contribute and Yours Don’t
This creates an imbalance that needs open discussion. Decide with your partner what you’ll accept and what it implies. If your partner’s parents contribute, ask whether there are expectations, such as guest list input or decision-making. Discuss how to include your own family in other ways, and be clear that contributions from one side don’t make your family less important.
What to Say When Guests Ask About Your Parents
Guests sometimes ask, “Aren’t your parents paying?” You don’t owe anyone an explanation. A simple answer works: “We’re planning this wedding ourselves, and we’re really enjoying it.” Then change the subject.
If Your Parents Are Divorced or Estranged
Plan around the relationships as they are. Decide separately what role each parent will have, brief your wedding party, assign someone trusted to manage seating and photos, and don’t depend on the day to repair conflict.
If a Parent Criticizes Your Budget Choices
Remember that criticism often reflects their own anxieties about how things look. Listen briefly, thank them, and keep the decision yours.
Sample Budget Plans for Self-Funded Weddings
These examples show how the same principles scale at different budgets. Percentages are approximate and vary by region.
The Lean Plan: About $6,000 for 40 Guests
A small Friday or Sunday wedding at a community hall or restaurant room. Catering and drinks take around half the budget, with a simple buffet and limited alcohol. Photography is booked for three to four hours. Attire is rented or pre-owned. Décor is minimal, using greenery and candles. Music is a playlist and speaker. The remaining money covers the license, officiant, a small cake, and contingency.
The Balanced Plan: About $15,000 for 70 Guests
An off-peak Saturday or a Friday at a venue with rentals included. Catering is a buffet or family-style meal with beer, wine, and one signature drink. Photography covers six hours. Attire is a mix of purchased and rented. A DJ is hired for a shorter package. Flowers and décor focus on one or two focal points. Stationery is mostly digital.
The Micro-Wedding Plan: About $8,000 for 20 Guests
A small gathering with a high-quality meal and strong photography. Because the headcount is small, you can spend more per person on food and atmosphere. The venue might be a private room or a rented home. Décor is simple, and live music is limited to the ceremony.
Use These as Templates, Not Targets
Your numbers will differ, but notice the pattern: guest count and venue drive the total, and priorities decide where the rest goes.
A Realistic Planning Timeline for Couples Saving as They Plan
Your timeline differs slightly because you’re building your fund while planning.
Twelve to Eighteen Months Before
Have the money conversation with parents, set your savings plan, open a dedicated account, decide priorities, and create a draft guest list. Choose a likely season and day of the week.
Nine to Eleven Months Before
Research and book your venue and caterer. Confirm your officiant, and start looking at photographers. Don’t pay major deposits until you’re confident your savings are on track.
Six to Eight Months Before
Book photography and music. Begin attire shopping and allow time for alterations. Create your wedding website and registry.
Three to Five Months Before
Send save-the-dates if needed, finalize your menu, plan décor, and arrange rentals, transportation, and accommodations.
One to Two Months Before
Send invitations, track RSVPs, confirm final headcount, finalize vendor details, and create a day-of timeline. Prepare final payments.
The Final Week
Confirm arrival times, pack an emergency kit, assign a trusted person to handle questions on the day, and rest. Eat, sleep, and spend time with your partner.
Alternatives to a Traditional Wedding
If your budget is far below the cost of a traditional wedding, you still have good options.
Micro-Weddings
With 10 to 30 guests, you can create a personal, high-quality experience at a manageable cost.
Courthouse Ceremony Plus Celebration
Marry at a courthouse or registry office, then host a relaxed dinner or party. This separates the legal ceremony from the celebration and reduces pressure.
Elopement
An elopement can be affordable and intimate. Check legal requirements for marrying in your chosen location, and consider a photographer to capture the day.
Marry Now, Celebrate Later
You can marry now and hold a larger celebration when your finances allow. This isn’t a failure. It’s a plan.
Backyard or Home Weddings
Hosting at a family or friend’s home can reduce venue costs, though you’ll need to budget for rentals, cleanup, parking, restrooms, and weather backups.
Common Mistakes When Paying for Your Own Wedding
Booking Before Setting a Budget
Falling in love with a venue before knowing what you can afford makes everything else feel like a compromise.
Counting Money You Don’t Have Yet
Plans built on expected gifts, promised contributions, or future raises can collapse. Plan with what you have and what you reliably save.
Ignoring Small Costs
Taxes, service charges, tips, alterations, postage, and last-minute purchases can add thousands.
Letting the Guest List Grow Quietly
“Just a few more” repeated many times can change your total significantly.
Overspending on Trends
Trends can lose meaning quickly. Choose items that mean something to you.
Forgetting the Relationship
Planning can dominate your time together. Schedule moments that have nothing to do with the wedding.
Comparing Yourself to Others
Social media shows highlights, not the debts and stress behind them. Your wedding doesn’t need to compete with anyone.
Frequently Asked Questions
Is it normal for parents not to pay for a wedding?
Yes. In many families and cultures, couples fund their own weddings. Parental contribution is never guaranteed, and plenty of couples pay for everything themselves.
How much should I spend on my wedding if I’m paying for it myself?
Spend only what you can pay without going into debt. Add your current savings to what you can save before the date, subtract about 10 percent for contingency, and treat the remainder as your budget, regardless of national averages.
Should I ask my parents for money if I don’t think they’ll offer?
It’s reasonable to ask once, politely, so you know where you stand. Make it easy for them to say no, and plan your budget around what you control.
How do I tell my parents we’re paying for the wedding ourselves?
Be direct and positive. Say that you’ve decided to plan around your own funds and want to keep them informed. Invite them to be involved in ways that suit them.
Can I have a say in everything if my parents aren’t paying?
Yes. You and your partner are the decision makers when you’re funding the wedding. You can still listen to opinions and include meaningful roles for parents without handing over control.
What if my partner’s parents are paying but mine aren’t?
Talk openly with your partner about expectations, and ask whether their parents’ contribution has conditions. Make sure both families are included and respected, and don’t let the imbalance become a measure of your family’s worth.
What should I cut first when money is tight?
Reduce the guest count first, since it affects nearly every cost. Then review alcohol, extra décor, favors, stationery, and optional rentals before cutting the items you’ve named as priorities.
Is it okay to have a small wedding because I can’t afford a big one?
Absolutely. Small weddings can feel more personal, allow higher quality for each guest, and reduce stress. Size doesn’t determine meaning.
Can I use a credit card to pay for my wedding?
You can, but only if you will pay the balance in full on time. Carrying a balance at a high interest rate can erase any benefit and add to your costs.
What if my parents offered money but want to control the guest list?
You can accept only if the conditions work for you. If they don’t, thank them and decline, or negotiate a specific number of invitations. Be clear about what you can and can’t accommodate.
Do I have to invite my parents’ friends if they aren’t paying?
No. The guest list is yours. You may invite a few close family friends if you wish, but you’re not obligated, especially if space and budget are limited.
How far in advance should I start planning if I’m saving as I go?
Twelve to eighteen months is ideal. It gives you time to save, compare vendors, and book popular dates without paying rush premiums.
How can I plan a wedding on a very small budget?
Choose a small guest list, an off-peak date, a simple venue, and a limited menu. Prioritize what matters most, such as food or photos, and keep everything else simple.
Are wedding insurance policies worth it?
They may be, especially if you’ve made large non-refundable deposits. Check what’s covered, such as vendor cancellation or extreme weather, and compare the cost with the amount at risk.
What if I feel sad that my parents aren’t helping?
That’s a normal reaction. Talk with your partner, a friend, or a counselor, and give yourself room to feel it without letting it shape your decisions.
Will paying for my own wedding affect my relationship with my parents?
It doesn’t have to. Clear communication, appreciation for non-financial help, and thoughtful boundaries usually keep relationships healthy.
Final Thoughts
Planning a wedding without your parents’ financial support asks more of you at the start, but it also gives you something valuable: a wedding built around your own priorities, your own budget, and your own decisions. Set your budget from real savings, choose your priorities, control the guest list, ask vendors direct questions, and keep family conversations honest and kind.
In the end, guests rarely remember how much a wedding cost. They remember how it felt: the people, the food, the laughter, and the sense that the day belonged to the couple. That is entirely within your reach, with or without anyone else’s money.